Implication of the One Big Beautiful Bill Act for New Vehicle Lenders
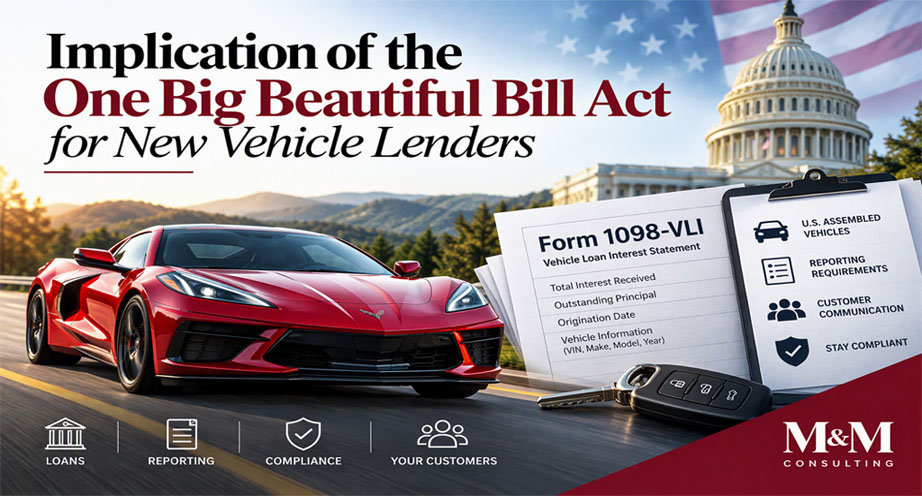
On July 4, 2025, President Trump signed into law the One Big Beautiful Bill Act (OBBBA, or OB3), which introduced a new interest tax deduction for customers financing (or refinancing) new passenger vehicles, applicable to new vehicle loans originated after December 31, 2024. One result is a corresponding increased reporting requirement on lenders, including banks and credit unions, which ratchet up this year after the temporary relief provided by the IRS for tax year 2025 elapsed.
Specifically, under regulations codified at IRS 6050AA, any lender that receives $600 or more in interest from any individual on a specified passenger vehicle loan must now also provide the IRS and borrowers with specific information by the end of January following the tax year. While the IRS did provide guidance offering some transitional relief for the 2025 tax year, lenders will now have to grapple with the full suite of reporting requirements, which - new this year - includes reporting certain information to the IRS in addition to standardized consumer reporting.
It’s important to note that implementing provisions of the final rule were only recently published in the federal register, (September 8, 2026), and while banking agencies have not released any new guidance, the IRS subsequently issued the final form 1098-VLI and its instructions. Unfortunately, the IRS rejected banking industry requests to let lenders issue 1098-VLI for all vehicle loans and let borrowers sort out eligibility.
While reporting requirements have crystallized, many bankers have not yet landed on how to best proceed and integrate the new requirements into their loan management systems. As we note above, the IRS places the burden of asset verification – that is, determining if the vehicle was assembled in the U.S. – directly on the lender, which among other things could impact the information lenders gather and retain when originating a new car loan. Many small/community banks and credit unions in particular may discover that finding and sorting information to meet new requirements is a more challenging aspect of the OB3 tax deduction than the actual reporting, especially those shops with antiquated loan systems or a reliance on highly manual processes. And as if that isn’t enough, penalties can accrue quickly for erroneous reporting, so lenders will want to plan early to get this right.
Basically, reporting requirements break down into two categories (the reporting obligation generally falls on the party receiving interest, but special rules apply when servicing occurs for another entity). Thankfully, the rules exclude leases, commercial vehicles, and fleets.
Information That Must Be Reported to Borrowers
Lenders must provide certain basic information to new vehicle borrowers by January 31 of the year following the tax year. Interest is only deductible on new (2025 and later), personal-use, U.S. assembled vehicles under 14,000 pounds. While the transition relief period allowed flexibility, lenders now must furnish the new IRS form 1098-VLI (Vehicle Loan Interest Statement) to applicable borrowers. Required fields include:
• Total interest received
• Outstanding Principal of the vehicle loan as of January 1, 2026 (if any)
• Origination Date
• Original loan principal
• Assignment date (if the financial institution acquired the loan or servicing rights in 2026)
• Vehicle details, such as the VIN; year, make and model; and U.S. assembly indicator
Information That Must be Reported to the IRS
• Borrower identifiers (name, TIN, etc.)
• Vehicle details including exact make, model, year of manufacture, and Vehicle Identification Number (VIN)
• Loan origination date and total outstanding principal balance
• Qualifying interest paid
The deduction only applies to vehicles that underwent final assembly in the United States. The National Highway Traffic Safety Administration (NHTSA) database is the final authority for whether a vehicle fits final assembly parameters; however, lenders with dated or manually intensive loan systems may find it useful to first sort VINs based in the first digit (of a traditional 17-digit VIN), as these indicate the country of assembly, with digits of 1, 4, and 5 representing the U.S. (while 2 = Canada, and 3 = Mexico, for example).
For lenders, best practice is to recognize that this is a requirement going forward and provide timely and adequate information to your members and customers, understanding that while the responsibility for accurately filing personal taxes lies with the taxpayer, the responsibilities to provide accurate information to file those taxes lies with your financial institution. Verifying that your loan management, servicing platform, and/or loan purchasing systems currently capture (and flag) the required data fields is a safer way to go for you and your customers. and institutions should get started assessing their systems and capabilities to understand any changes or work they’ll need to invest to get this right the first time. Finally, being prepared to send 1098-VLIs earlier than the deadline could help give your institution time to correct any errors or identify borrowers inadvertently overlooked.
Nov 18, 2026, 8:53:33 AM